
October 29, 2021
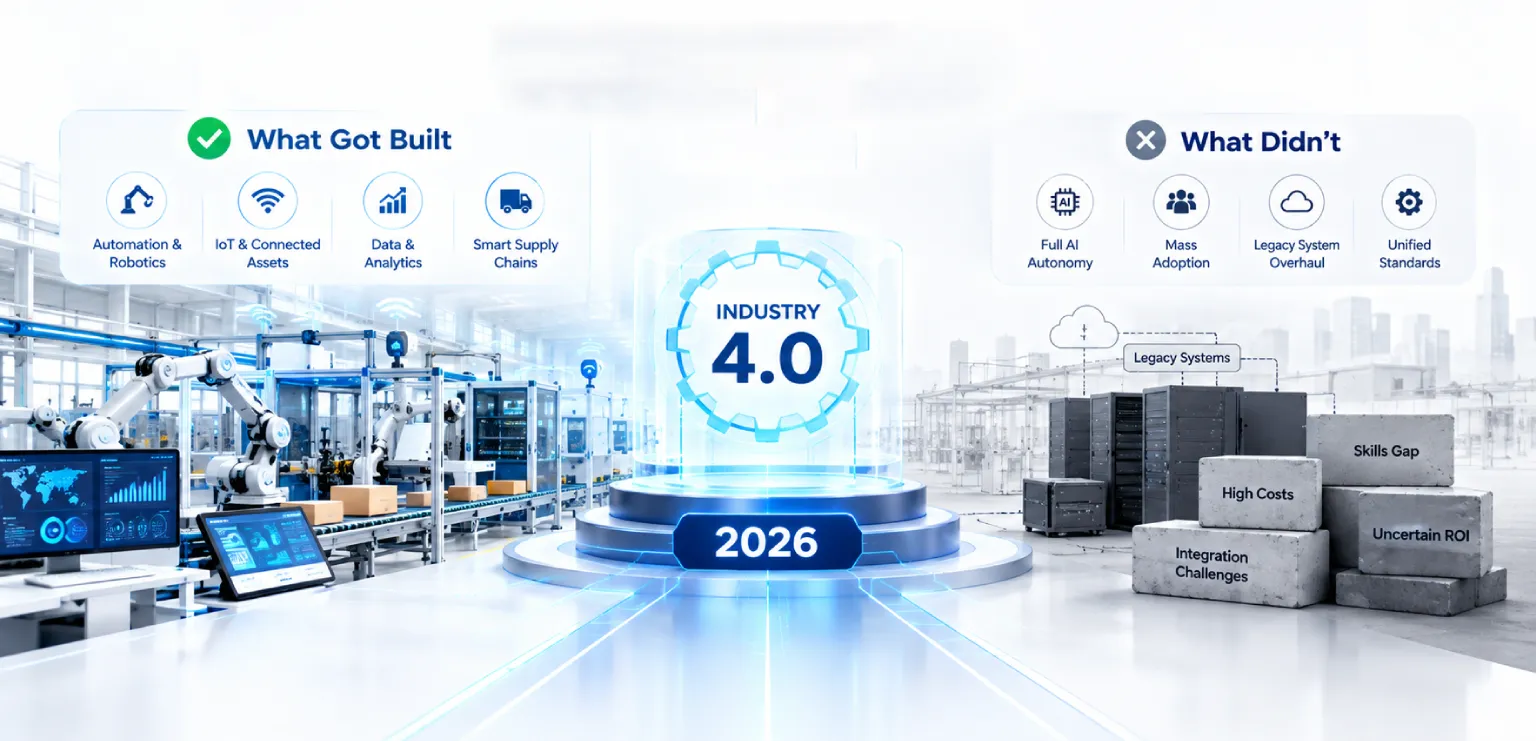
Industry 4.0 in 2026: What Actually Got Built, and What Didn’t
Enjoying this article?
Share it with the world!


Industry 4.0 Explained: Adoption, ROI and Reality in 2026
| ⚡ Quick Answer Industry 4.0 is the use of connected sensors, real-time data, and automated decision-making to run physical production. After roughly a decade of investment, adoption is real but uneven: most manufacturers have sensors and cloud analytics in place, far fewer have AI running at production scale, and fewer still have deployed plant-wide. The bottleneck is no longer the technology — it is data foundations and the workforce that has to operate the result. |
When this article was first published in 2021, Industry 4.0 was mostly a forecast. Connected factories were something you read about in vendor case studies, the market projections were enormous, and the question every manufacturer was asking was whether any of it would actually arrive.
Five years later, the question has changed. It arrived. Just not evenly, and not in the shape most people expected.
This is a rewrite of the original piece, using what the data now shows rather than what the projections once promised.
What Industry 4.0 Actually Is
Industry 4.0 is the point at which physical production becomes instrumented, connected, and partly self-directing. Sensors on machines generate continuous data, that data flows to systems that can analyse it in real time, and some decisions get made without waiting for a human to notice a problem.
One clarification worth making, because the terms get used interchangeably and shouldn’t be. Industry 4.0 is not a synonym for IoT. The Internet of Things is one technology inside it — the sensing layer. Industry 4.0 is the operating model that emerges when sensing, connectivity, analytics, and automation work together. You can buy IoT. You cannot buy Industry 4.0.
| Four Industrial Revolutions
Each revolution builds on the last — 4.0 adds decision-making to the automation that 3.0 delivered |
The third revolution gave machines instructions. The fourth gives them information, and increasingly, the authority to act on it.
What the Data Actually Shows in 2026
Deloitte surveyed 600 manufacturing executives for its 2025 Smart Manufacturing and Operations research. The headline finding is about intent, and it is strong.
Source: Deloitte 2025 Smart Manufacturing and Operations Survey, 600 manufacturing executives. |
| The Reality That 28-point gap between sensors deployed and AI running at scale is where Industry 4.0 actually sits in 2026. The instrumentation happened. The intelligence layer, for most manufacturers, has not. |
A second figure makes the same point from a different angle. Roughly 46% of manufacturers use industrial IoT at facility level — meaning most have it running somewhere, and the majority have not taken it plant-wide. The Manufacturing Leadership Council’s 2026 survey finds 72% of respondents place themselves at mid-level maturity, with nearly half now scaling beyond single-site pilots.
Pilots are no longer the problem. Scaling past them is.
Why You Should Ignore the Market Size Figures
The original version of this article quoted a market forecast. Most articles on this topic still do. It is worth explaining why we have dropped it.
Here is what four research firms currently say the IoT-in-manufacturing market will be worth in 2026:
| Same market, same year, a sevenfold spread. The differences come from what each firm counts as “IoT in manufacturing” — hardware only, or hardware plus platforms plus services plus connectivity. None of them are wrong. All of them are useless for planning your own investment. |
Adoption data tells you something. Market forecasts, in this category, mostly tell you which report you read.
| Stuck between pilot and plant-wide? That is where most manufacturers are, and the blocker is usually data architecture rather than shop-floor technology. We can review what you have running and what it would take to scale it. |
What Changed Between 2021 and Now
Three things arrived that were not part of the original conversation.
| Agentic AI moved from concept to deployment Deloitte’s 2026 outlook identifies agentic AI as the technology most likely to elevate smart manufacturing next — systems that can identify and engage alternative suppliers during a disruption, generate shift handover reports autonomously, and capture institutional knowledge from retiring staff before it walks out the door. |
| Physical AI became a near-term plan, not a demo A Manufacturing Leadership Council survey in early 2025 found nearly a quarter of manufacturers plan to deploy robots with meaningful autonomy within two years — more than double current adoption rates. |
| The constraint moved from hardware to data In 2021 the question was whether you could afford the sensors. In 2026 the sensors are cheap and the question is whether the data they produce is clean, connected, and usable. That is why the 57% and 29% figures diverge. |
The Part Most Coverage Gets Wrong
Two findings from the same Deloitte research sit uncomfortably together, and both are worth knowing.
|
|
More than a third of the 600 executives surveyed named their single biggest concern as equipping workers with the skills to make smart manufacturing work. Not funding it. Not selecting vendors. Staffing it.
This is the same pattern that shows up in every large digital transformation programme: the technical work is tractable, the organizational work is where it stalls. Manufacturing is not an exception. It may be the clearest example.
What Returns Actually Look Like
Manufacturers in the Deloitte survey self-report gains of up to 20% in production output and employee productivity, and up to 15% in unlocked capacity. These are executive self-assessments rather than independently audited results, so treat them as directional.
| A defensible business case A 10% to 20% improvement in production output is the range the survey data supports. It is a stronger number to take to a board than a vendor claim precisely because it is modest and sourced. Build the case on that, and treat anything above it as upside. |
Predictive maintenance remains the single largest application, holding roughly 30% of deployments and growing faster than any other use case — largely because the value is easy to measure. Avoided downtime has a price everyone already agrees on.
Who Should Be Moving on This Now
The original version of this article listed six organizational profiles. They have held up well, so they are kept here with the reasoning updated.
|
How to Sequence It
The 57%-to-29% gap is a sequencing lesson. Manufacturers who bought AI before fixing their data are the ones sitting in the gap.
Most manufacturers are between steps 1 and 2. The ones that skipped step 2 are the ones stuck. |
Step 1 — Instrument and connect. Sensors, connectivity, and a place for the data to land. Most manufacturers have done this. It is table stakes rather than advantage.
Step 2 — Fix the data foundation. Consistent formats, resolved identities across systems, pipelines that keep up with production, and governance over who sees what. This is unglamorous and it is where the 28-point gap lives. Our data engineering practice exists largely for this stage.
Step 3 — Deploy analytics and prediction. Predictive maintenance first, because the value is measurable. Then quality inspection, then throughput optimization. Analytics and BI is what turns sensor output into a decision.
Step 4 — Add autonomy selectively. Agentic and physical AI belong on top of a working data layer, not instead of one. ML engineering is the discipline that keeps these systems reliable once they are making decisions unsupervised.
Frequently Asked Questions
| What is Industry 4.0 in simple terms? It is manufacturing where machines are instrumented with sensors, connected to each other and to central systems, and increasingly able to act on what the data shows without waiting for a person to intervene. The first revolution was steam, the second electricity and mass production, the third computers and programmable control. The fourth adds decision-making. |
| Is Industry 4.0 the same thing as IoT? No, and the two get conflated constantly. IoT is the sensing and connectivity layer — one component. Industry 4.0 is the operating model that results when sensing, analytics, automation and decision-making work together. Buying IoT hardware does not make a plant an Industry 4.0 plant. |
| What ROI should we expect? A 10% to 20% improvement in production output is the range best supported by survey data from manufacturing executives. Unlocked capacity of up to 15% is also commonly reported. These are self-assessments rather than audited figures, which makes them a more defensible basis for a business case than vendor claims, not less — they are modest and they are sourced. |
| Where do most Industry 4.0 programmes get stuck? Between a working pilot and plant-wide deployment. The technology proves out at one site, then scaling exposes that the data is inconsistent across facilities, the integrations were bespoke, and nobody was trained to operate it at volume. Roughly 46% of manufacturers are running industrial IoT at facility level; far fewer have gone plant-wide. |
| Should a mid-sized manufacturer bother, or is this for large enterprises? The barrier has dropped considerably. Cloud-based platforms for analytics and operations management remove most of the infrastructure cost, and managed AI services remove the need for in-house specialists. Smaller manufacturers who move early on foundational capability tend to gain ground; those who wait find the gap widening as larger competitors scale. |
| Will this replace the workforce? The projection is that more than 81% of manufacturing task hours remain human-driven. The more pressing issue is the opposite one: human capital scores as the lowest-maturity category in smart manufacturing assessments, and more than a third of executives name workforce skills as their single biggest concern. The constraint is people to run these systems, not people displaced by them. |
Where It Is Actually Leading
The 2021 version of this article asked where Industry 4.0 was leading us. Five years of data gives a clearer answer than a forecast could.
It is leading toward plants where the sensing is done, the data foundation is half-built, and the intelligence layer is arriving unevenly — faster at manufacturers who fixed their data first, slower at those who bought models before pipelines. The technology stopped being the hard part somewhere around 2023.
What remains hard is the same thing that has always been hard: connecting systems that were never designed to talk to each other, and equipping people to work differently once they do.
| Embrace the future with Industry 4.0 Close the gap between sensors deployed and intelligence delivered. Impressico works with manufacturers on the unglamorous middle of this — the data pipelines, system integrations, and analytics foundations that turn instrumented plants into ones that actually decide faster. |