
September 17, 2021
AI in Financial Services 2026: Adoption Is Near-Universal. Profitability Isn’t
Enjoying this article?
Share it with the world!


Digital Transformation in Finance: The 2026 Reality
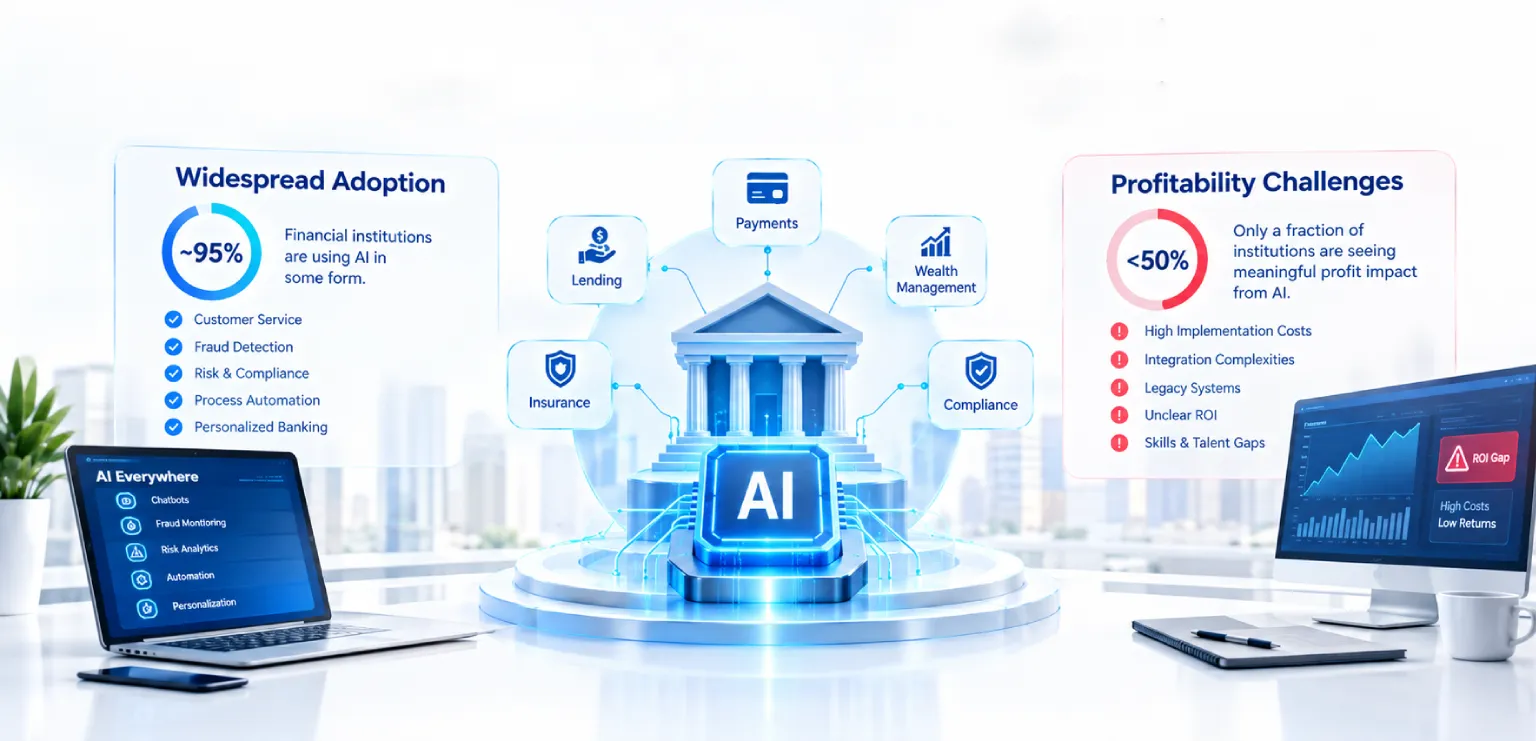
| ⚡ Quick Answer Digital transformation in financial services has moved past the question of whether to adopt AI — 81% of firms already have, at some level. The open question is why only 40% report improved profitability from it. The evidence points at data quality and legacy systems rather than model selection: most institutions are still piloting because their data cannot support production deployment, not because the technology does not work. |
For most of the last decade, writing about digital transformation in finance meant making a case for it. Mobile banking was still displacing branches, fintech was still the disruptor, and the argument was about whether incumbents would move fast enough.
That argument is settled. Adoption happened. What did not happen, for a substantial share of the industry, is the return.
This article looks at where digital transformation in financial services actually stands, using the most substantial evidence base currently available, and at what separates the institutions seeing results from the ones still waiting.
Where Adoption Actually Stands
628 organisations, 151 jurisdictions, one clear pattern
The Cambridge Centre for Alternative Finance published its 2026 Global AI in Financial Services Report in April, produced with the Bank for International Settlements, the IMF, the World Economic Forum, the World Bank Group and others. It surveyed 628 organisations — 203 fintechs, 149 traditional financial institutions, 146 AI vendors and 130 central banks and regulators — across 151 jurisdictions.
Four in five financial services firms are deploying AI at some level. But the maturity distribution underneath that headline is where the useful information sits.
| AI Maturity in Financial Services
Source: Cambridge Centre for Alternative Finance, 2026 Global AI in Financial Services Report. |
Forty-one percent are still at pilot stage. Fourteen percent describe their deployment as transformational. The report’s own framing is an industry “in mid-transition, marked by a significant execution gap between widespread early-stage adoption and true strategic transformation.”
The Number Most Coverage Leaves Out
Adoption figures are easy to celebrate. Outcome figures are harder, which is why they appear less often.
|
|
| The Reality Eighty-one percent adopted. Forty percent got a profitability improvement. That means roughly half of the institutions that deployed AI are, by their own assessment, no better off financially for having done so. |
The report notes that profitability outcomes correlate with AI investment levels and workforce preparedness — not with which models or vendors were selected. That is a useful thing to know before signing the next platform contract.
Why the Gap Exists: It Is the Data
The Cambridge report identifies persistent constraints in data quality and legacy systems as the structural divide separating institutions that transform from institutions that pilot indefinitely. Deloitte’s banking and capital markets research puts numbers on how bad that constraint is.
Source: Deloitte Banking & Capital Markets Data and Analytics Market Survey. |
A model cannot outperform the data it is given. When nine out of ten data users inside a bank cannot reliably get at the information they need, the constraint on AI is not the AI.
This is the same pattern that shows up across every sector deploying AI at scale, and it is why data readiness deserves assessment before model selection rather than after. Financial services has a harder version of the problem than most, because the systems holding the data are frequently decades old and were never designed to share it.
| Piloting for longer than planned? Forty-one percent of the industry is in the same position, and the blocker is usually upstream of the model. We can assess where your data actually stands before you commit to the next phase. |
What the $200 - 340 Billion Figure Actually Means
The most quoted statistic in this category comes from the McKinsey Global Institute: generative AI could add between $200 billion and $340 billion in annual value across the global banking sector, equivalent to roughly 9–15% of operating profits, largely through productivity gains.
| Read it carefully That is a potential ceiling across the entire industry, not a realised gain and not a per-institution projection. It describes what the sector could capture if adoption matured everywhere. Given that 43% of firms currently report no profitability change at all, the gap between the ceiling and the floor is the whole story. |
McKinsey’s narrower near-term estimate is more useful for planning: up to 20% in net cost reductions as adoption scales. Their banking review also finds that first movers stand to gain roughly a 4% return-on-tangible-equity advantage, while slower movers end up with an uncompetitive cost base. The distribution matters more than the total.
Where AI Is Actually Delivering in Finance
The use cases that survive contact with production
A consistent pattern runs through the research: the use cases that reach production are the ones where the value is measurable and the failure mode is contained.
| Fraud detection The most widely deployed application, and the easiest to justify. Avoided losses have an agreed price, the models improve with volume, and a false positive costs a customer call rather than a regulatory incident. |
| Compliance and regulatory analysis Reading, comparing and summarising regulatory documents is high-volume work with clear inputs and reviewable outputs. Citigroup’s use of generative AI to assess more than a thousand pages of new capital rules is the frequently cited example. |
| Client onboarding and KYC Document extraction, identity verification and risk screening are structured, repetitive, and currently slow. The gain is in cycle time, which is directly measurable. |
| Underwriting and credit decisioning support Interpreting large volumes of documents and contracts to support a human decision. Note “support” — the regulatory position on fully automated credit decisions remains unsettled in most jurisdictions. |
The common thread is that each has a measurable baseline. Institutions that cannot say what a process costs today will struggle to demonstrate that AI improved it — which is the measurement discipline covered in our guide to measuring ROI from generative AI projects.
Agentic AI: Fintechs Are Ahead, and the Gap Is Measurable
The Cambridge research finds fintechs ahead of traditional financial institutions on every maturity metric, and the agentic AI figures show it most clearly.
|
|
Two findings from the same report complicate the usual explanation that incumbents lack budget. First, 53% of respondents spend under $100,000 a year on AI and still report high maturity in generative and agentic AI. Second, firms in emerging markets and developing economies report higher deployment levels than those in advanced economies.
Neither pattern is consistent with spending being the constraint. Both are consistent with legacy systems and organisational readiness being the constraint — which is also why legacy modernization keeps appearing on the critical path of AI programmes that were not supposed to be modernization programmes.
| Looking further out, 81% of industry respondents expect agentic AI to be meaningfully achieved by 2030, making it the clearest growth frontier the report identifies. |
The Governance Problem Nobody Owns
One of the report’s more uncomfortable findings is a perception gap between the firms buying AI, the firms selling it, and the regulators supervising it.
On both measures, the vendors selling AI into financial services rate the risk materially lower than the institutions running it and the regulators supervising it. That is worth factoring into vendor conversations.
Bryan Zhang, who leads the Cambridge Centre for Alternative Finance, characterised the sector as one where adoption is remarkable but “accountability for AI failures is unresolved.” For regulated institutions, that is not an abstract concern — it is a question of who answers when an autonomous system gets a decision wrong.
What This Means If You Run a Financial Institution
Four things follow from the evidence above.
|
None of this is unique to finance. What is unique to finance is the regulatory exposure when it goes wrong, and the age of the systems holding the data — which is why the sector shows a wider spread between leaders and laggards than most.
Frequently Asked Questions
| What is digital transformation in financial services? It is the integration of digital technology across how a financial institution operates and delivers value — historically meaning channel digitisation and core modernisation, and now meaning AI embedded in fraud detection, compliance, onboarding and credit processes. The definition has not changed much; what counts as table stakes has. |
| How many financial institutions are actually using AI? 81% are deploying it at some level, according to the Cambridge Centre for Alternative Finance’s 2026 survey of 628 organisations across 151 jurisdictions. But 41% remain at pilot stage, 26% are scaling, and only 14% describe their deployment as transformational. |
| Is AI making banks more profitable? For some. 40% of surveyed firms report increased profitability from AI, while 43% report no change. The outcome correlates with investment level and workforce preparedness rather than with technology choices. The widely quoted $200–340 billion McKinsey figure is an industry-wide potential ceiling, not a realised or per-institution number. |
| Why are fintechs ahead of traditional banks? Not primarily budget. 53% of respondents spend under $100,000 annually on AI yet report high maturity, and firms in emerging markets report higher deployment than those in advanced economies. The consistent differentiators are legacy system constraints and data accessibility — both of which fintechs largely do not carry. |
| Which AI use cases work best in financial services? Fraud detection is the most widely deployed and easiest to justify. Compliance and regulatory document analysis, client onboarding and KYC, and underwriting support follow. The pattern is that each has a measurable current-state baseline and a contained failure mode. |
| What is the biggest barrier to AI in banking? Data. More than 90% of data users at banks report that the data they need is often unavailable or takes too long to retrieve, and 81% cite data quality as a top challenge. Legacy systems that were never designed to share data compound the problem. Model selection is rarely the constraint. |
Conclusion
Digital transformation in financial services is no longer a question of intent. Four in five institutions are deploying AI, and the technology has demonstrably worked in fraud, compliance and onboarding.
The open question is why that has translated into profitability for two in five and nothing measurable for a similar number. The evidence points consistently at the same places: data that cannot be retrieved, systems that will not integrate, and workforces that were not prepared for what arrived.
None of those are AI problems. They are the problems AI made visible.
| Move from piloting to production Get into the 14%, not the 41%. Impressico works with financial institutions on the layer underneath the models — data engineering, legacy integration, and the governance that regulated deployment requires. |